
On-spot export customs procedures | Detailed instructions
On-spot export customs procedures have just undergone a comprehensive reform after years of regulations scattered across multiple different documents, as the National Assembly passed Law No. 90/2025/QH15 amending the Customs Law and the Value-Added Tax Law (effective from July 1, 2025).
This was followed by Decree 167/2025/ND-CP amending Decree 08/2015/ND-CP, and in particular Circular 121/2025/TT-BTC, which directly amends Article 86 of Circular 38/2015/TT-BTC and officially took effect on February 1, 2026. This is the most significant update to the on-spot import-export model in many years.
On-spot export is a distinctive form of foreign trade activity, in which goods are bought and sold under a contract with a foreign trader but are delivered and received directly within Vietnam – common with processed goods, goods traded with export processing enterprises, or goods designated for delivery to a third party in Vietnam.
On-spot export customs procedures therefore differ in many respects from standard export procedures, requiring businesses to clearly understand the applicable subjects, documentation, and deadlines under the latest regulations. The article below compiles all legal grounds, applicable subjects, documentation, procedures, and important notes for on-spot export customs procedures, updated as of September 2026.
1. What Is On-Spot Export and How Does It Differ From Standard Export
On-spot export is a form in which goods are sold by a Vietnamese business to a foreign trader under a foreign trade contract, but at the buyer’s instruction, the goods are delivered directly to another business in Vietnam instead of being physically transported out of the country’s territory. This is the fundamental difference that means on-spot export customs procedures do not involve an actual international transport stage, unlike other export forms.
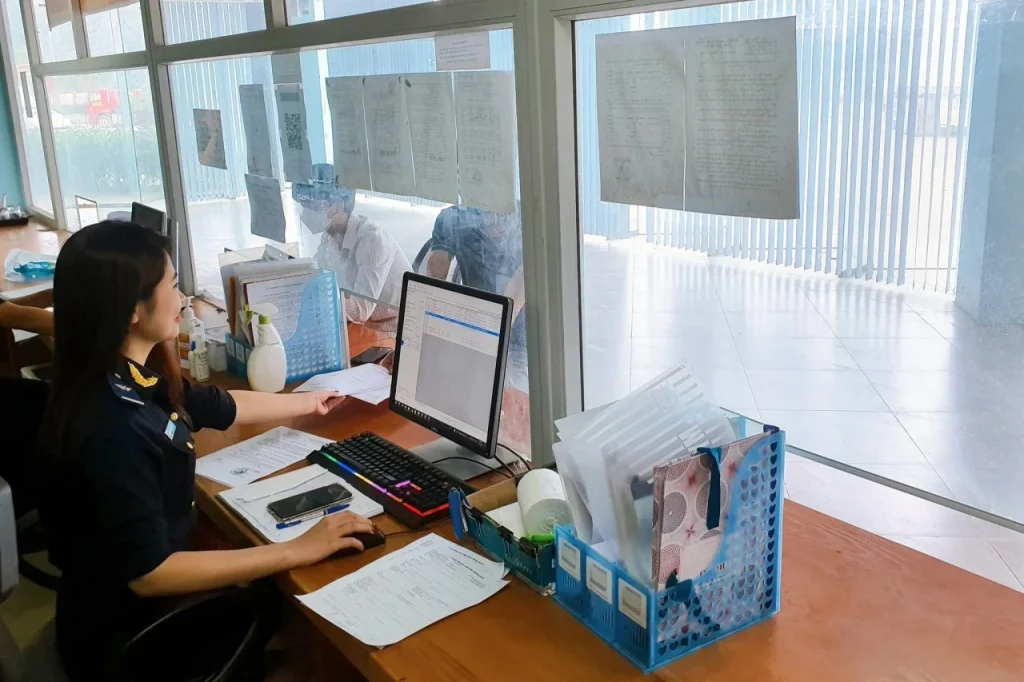
This form is common in processing supply chains and export production involving multiple domestic stages, or when a foreign business orders raw materials or semi-finished products for another business in Vietnam to continue producing or processing before the goods are officially exported abroad.
2. Legal Basis Governing On-Spot Export Customs Procedures
| Legal Document | Regulated Content |
|---|---|
| Law No. 90/2025/QH15 (effective from July 1, 2025) | Amends the Customs Law and the Value-Added Tax Law, unifying the concept and tax policy applicable to on-spot import-export goods |
| Decree 08/2015/ND-CP, as amended by Decree 167/2025/ND-CP | Provides detailed guidance for implementing the Customs Law on procedures, inspection, supervision, and customs control, including provisions on on-spot import-export goods |
| Circular 38/2015/TT-BTC, as amended by Circular 39/2018/TT-BTC and Circular 121/2025/TT-BTC (effective from February 1, 2026) | Article 86 directly regulates customs procedures for on-spot export and import goods – this is the key provision that was just amended |
| Decree 292/2026/ND-CP (effective from September 5, 2026, replacing Decree 69/2018/ND-CP) | General regulations on foreign trade management, applied concurrently to on-spot export goods subject to specialized management lists |
Important new point: Previously, regulations on on-spot import-export were scattered and lacked consistency across multiple documents. From 2026, with the rollout of the Smart Customs model, the declaration process has been streamlined: the exporter declares the on-spot export declaration using the appropriate type code (E21 for processed goods, B11 for ordinary trading goods), clearly stating the bonded transport destination location code and the tax code of the on-spot importing business directly on the electronic system, significantly shortening the time needed to reconcile information between the export and import sides.
3. Subjects Applicable to On-Spot Export Customs Procedures
| Goods Group | Description | Reference Type Code |
|---|---|---|
| Processed products, leased/borrowed equipment, surplus materials | Processed products; leased or borrowed machinery and equipment; surplus raw materials and supplies; scrap and defective products under a processing contract as regulated | E21 (processed goods) |
| Goods traded between a domestic business and an export processing enterprise/non-tariff zone enterprise | Goods traded between a Vietnamese business and an export processing enterprise or a business located in a non-tariff zone | B11 (trading goods) |
| Goods traded with a foreign trader not present in Vietnam | Goods traded between a Vietnamese business and a foreign organization or individual with no presence in Vietnam, where the foreign trader designates delivery to another business in Vietnam | B11 or per separate guidance |
4. Conditions for Applying On-Spot Export Customs Procedures
| Condition | Content |
|---|---|
| Sales contract clearly states the on-spot delivery terms | The foreign trade contract signed with the foreign trader must clearly state that the goods are delivered and received in Vietnam as designated |
| Information must be consistent between the export and import sides | Information on the on-spot export declaration and the on-spot import declaration must match in terms of quantity, value, and HS code |
| Compliance with the deadline for completing on-spot import procedures | The on-spot importer must complete procedures within 15 working days from the date the export goods are cleared |
5. Documentation Required for On-Spot Export Customs Procedures
| Document | When to Prepare | Important Notes |
|---|---|---|
| Foreign trade contract with the foreign trader | Before declaration | Must clearly state the on-spot delivery terms and the name of the receiving business in Vietnam |
| On-spot export customs declaration (type code E21/B11) | When processing on the VNACCS system | Must state the bonded transport destination location code and the tax code of the on-spot importing business |
| Commercial Invoice | Before customs declaration | Reflects the sales transaction with the foreign trader even though the goods do not leave Vietnam |
| Export permit (if the goods are subject to specialized management) | Before customs clearance | 01 original if exporting once, or 01 copy together with a deduction monitoring slip if exporting multiple times |
| Notice of inspection exemption/specialized inspection results (if applicable) | Before customs clearance | 01 original as required by the applicable specialized law |
6. Procedure for Carrying Out On-Spot Export Customs Procedures
Step 1: Determine which on-spot export group the shipment belongs to
The business confirms that its goods fall under one of the three groups eligible for the on-spot export form – this is the first step in on-spot export customs procedures, which determines the appropriate declaration type code.
Step 2: The exporter declares the on-spot export declaration
The exporting business declares the on-spot export declaration on the VNACCS system, using type code E21 (processed goods) or B11 (trading goods), clearly stating the bonded transport destination location code and the tax code of the on-spot importing business.
Step 3: The customs system processes and clears the export declaration
Once the system receives, channels, and clears the export declaration, this is considered the point at which the exporter’s customs obligation is completed.
Step 4: The on-spot importer declares the corresponding import declaration
The business receiving the goods in Vietnam must declare the on-spot import declaration within 15 working days from the date the export declaration is cleared, and the information must match the previously declared export declaration.
Step 5: Reconciliation, finalization of documentation, and record-keeping
Both businesses retain the complete customs documentation, contracts, and invoices to support post-clearance inspection if required by the customs authority.
7. Common Risks When Carrying Out On-Spot Export
| Risk | Symptom | Prevention |
|---|---|---|
| The on-spot importer declares more than 15 days late | Violates the prescribed deadline and may be subject to administrative penalties | Coordinate closely between both parties and track the clearance schedule to declare within the deadline |
| Information between the export and import declarations does not match | The customs system rejects the reconciliation, and the procedure cannot be completed | Carefully cross-check quantity, value, and HS code before both parties declare |
| Unclear determination of the concept of “foreign trader not present in Vietnam” | Difficulties applying the procedure, requiring additional guidance from specialized authorities | Consult a customs unit or forwarder experienced with this type of transaction |
| Incorrect declaration type code | Subject to back-taxation, customs clearance delays, and required declaration amendments | Correctly determine the nature of the transaction (processing or trading) before choosing code E21/B11 |
FAQ – Frequently Asked Questions About On-Spot Export Customs Procedures
Question 1: Does on-spot export require goods to be transported out of Vietnam?
No. The defining characteristic of on-spot export customs procedures is that goods are delivered and received directly between two businesses in Vietnam, as designated by the foreign trader, with no actual transport across the border.
Question 2: What is the latest legal document governing on-spot export?
Currently, it is Circular 121/2025/TT-BTC (amending Article 86 of Circular 38/2015/TT-BTC), effective from February 1, 2026, together with Law No. 90/2025/QH15 and Decree 167/2025/ND-CP amending Decree 08/2015/ND-CP.
Question 3: How long does the on-spot importer have to complete the procedure?
The on-spot importer must complete customs procedures within 15 working days from the date the on-spot export declaration is cleared.
Question 4: Which type code is typically used when declaring on-spot export?
Businesses typically use type code E21 for processed goods or B11 for ordinary trading goods, depending on the nature of the contract and the relationship between the parties involved in the transaction.
How Does 3W Logistics Support On-Spot Export Customs Procedures?
As a freight forwarding company registered as an OTI-NVOCC with an FMC bond in the United States, holding an SCAC Code to self-file AMS/ISF declarations directly, and with experience handling a wide range of import-export types, 3W Logistics supports businesses through the entirety of on-spot export customs procedures – from advising on the correct type code, to preparing documentation, through to completing the reconciliation of declarations between both parties.
- Consulting to determine the applicable subject and correct type code: Helping businesses distinguish between E21, B11, and special cases involving foreign traders not present in Vietnam.
- Support coordinating between the on-spot exporter and importer: Ensuring information on both declarations matches to avoid issues during reconciliation.
- Electronic customs declaration (VNACCS): A professional team processing declarations on time, staying closely updated on changes under Circular 121/2025/TT-BTC.
- Related transport service consulting: Full-service support for businesses with both on-spot export and standard international export activities within the same supply chain.
Why choose 3W Logistics: With offices in Ho Chi Minh City, Hanoi, and Hai Phong, and a team that stays closely updated on the latest legal changes regarding on-spot import-export, 3W Logistics ensures businesses follow the correct process, meet all deadlines, and avoid penalty risks from the very first time applying this type of procedure. – Ms. Apple, CCO of 3W Logistics
Head Office – 3W Logistics Ho Chi Minh City Branch
Address: 34 Bach Dang, Tan Son Hoa Ward, Ho Chi Minh City
Hotline: +84 28 3535 0087
____________________________
3W Logistics Hanoi Branch
Address: 81A Tran Quoc Toan, Cua Nam Ward, Hanoi
Hotline: +84 24 3202 0482
____________________________
3W Logistics Hai Phong Branch
Address: 8A Lot 28 Le Hong Phong, Gia Vien Ward, Hai Phong
Hotline: +84 225 355 5939
____________________________
3W LOGISTICS CO., LTD – We here serve you there!
Email: info@3w-logistics.com
Website: www.3w-logistics.com
Ms. Apple is the CCO (Chief Commercial Officer) at 3W Logistics, with over 10 years of experience in sales and business operations management.
At 3W Logistics, Ms. Apple is responsible for commercial strategy, corporate customer development, managing a team of more than 50 sales professionals, and improving business performance in the logistics sector.
With practical experience in sales management and market development, Ms. Apple shares professional insights on business logistics solutions, international transportation, freight forwarding, customer management, trade lane development, and growth strategies in the logistics industry.


